Despite a small increase in DWC, strong inventory management saw DIO fall to its lowest level in five years.
Cost-of-living pressures continued to drive value-focused consumer behaviour in FY26. Discretionary retail conditions weakened further as interest rates remained elevated, geopolitical uncertainty persisted and household budgets remained constrained. Despite these headwinds, 83% of the sample delivered revenue growth, with 53% also improving gross margins through a combination of promotional discipline, cost control and digital initiatives.
From a working capital perspective, average DWC increased by 0.4 days to 42.1 days, with performance evenly split across the sample as 50% of companies showed improvement. Inventory management remained a key focus, with DIO falling 2.9 days to 113.4 days, the lowest level in five years, driven by the clearance of excess stock, range optimisation and the exit of underperforming categories. However, this improvement was not uniform, with several larger operators deliberately carrying higher inventory levels to support product availability and mitigate future cost increases, while others had difficulty forecasting demand.
Average DSO increased by 0.4 days to 15.4 days, and DPO fell by 0.1 days to 54.7 days. Performance varied across the sample, with 47% of companies reducing DPO and several retailers recording material movements driven by supplier finance arrangements.
Average DWC remains below Asia but above Europe and the US. Australian retailers continue to benefit from a relatively fast cash collection cycle, with DSO lower than all three international regions. However, these benefits are partly offset by shorter supplier payment terms, with DPO remaining below international peers.
Looking ahead to FY27, consumer spending is expected to remain subdued, while freight costs and broader input cost inflation will continue to place pressure on margins and cash flow. As a result, disciplined inventory management and optimisation of supplier terms are likely to remain key drivers of working capital performance and liquidity.


Net working capital performance
Financial Year
Days | 2025 | 2026 | Change |
|---|---|---|---|
DSO | 15.0 | 15.4 | 0.4 |
DIO | 116.3 | 113.4 | (2.9) |
DPO | 54.8 | 54.7 | 0.1 |
DWC | 41.7 | 42.1 | 0.4 |
International Benchmarking
Days | Asia | EU | US |
|---|---|---|---|
DSO | 39.4 | 23.5 | 17.9 |
DIO | 101.7 | 122.8 | 87.6 |
DPO | 78.2 | 93.7 | 95.1 |
DWC | 49.6 | 31.2 | 26.1 |
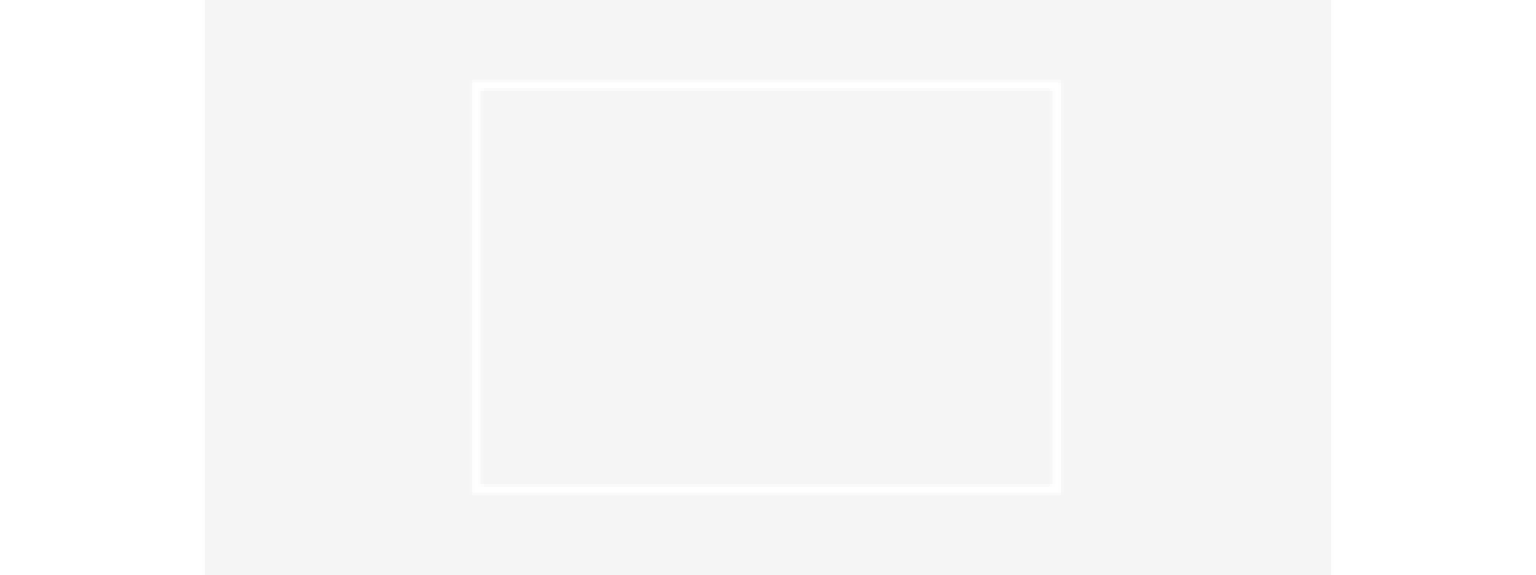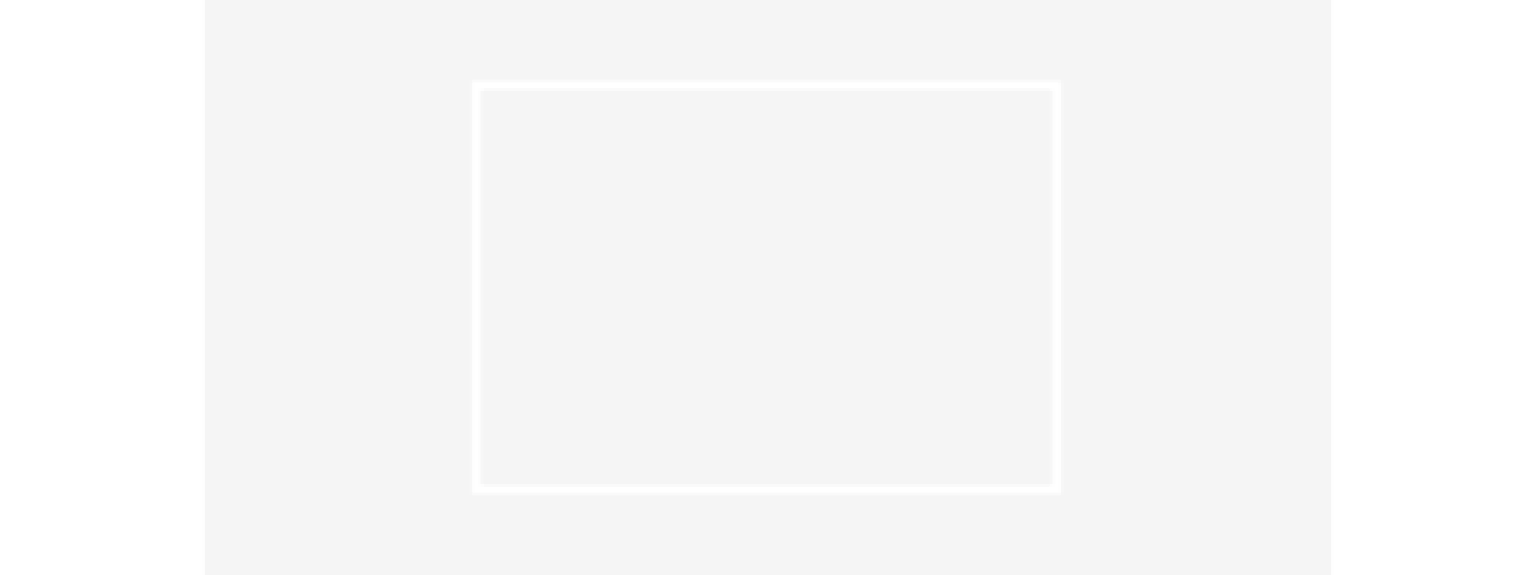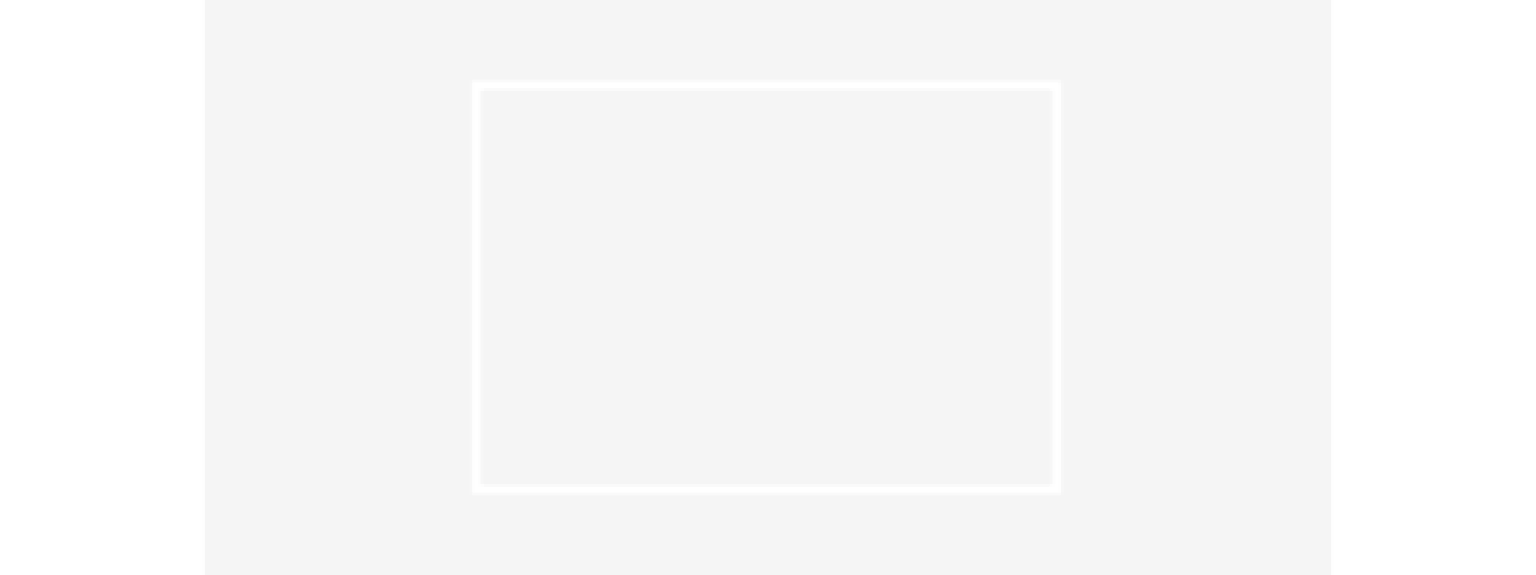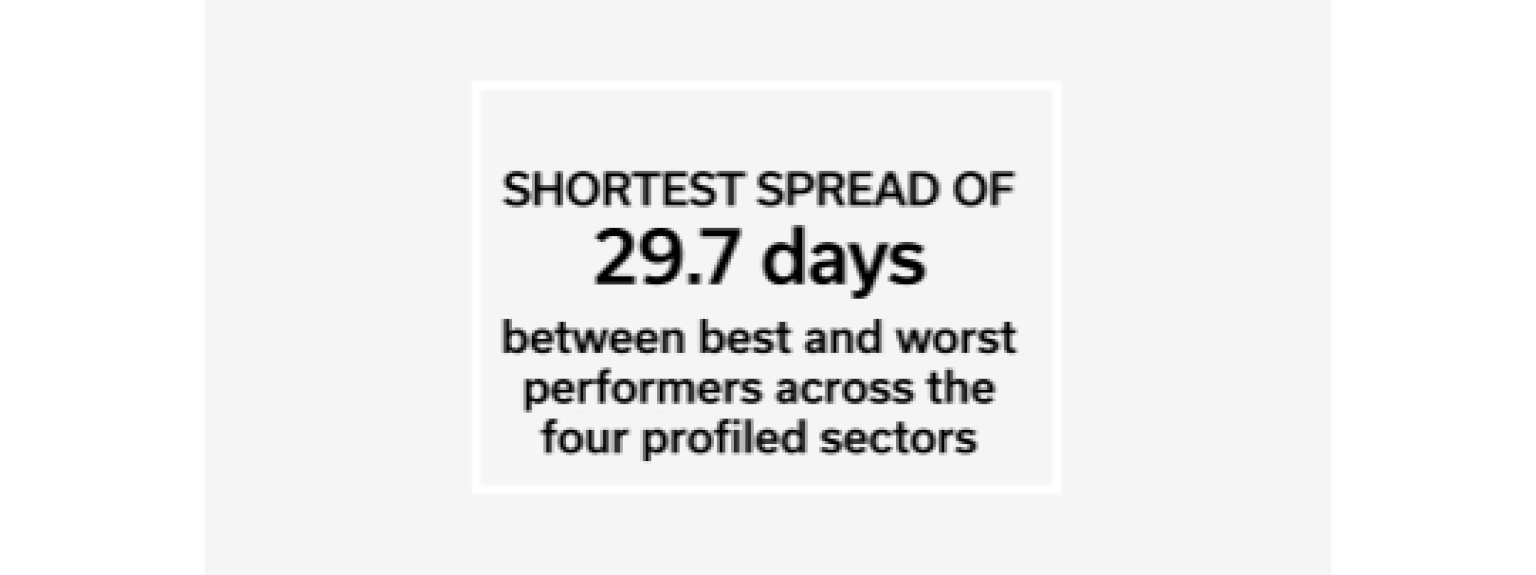
Best & Worst
Days | Best | Worst | Spread |
|---|---|---|---|
DSO | - | 71.4 | 71.4 |
DIO | 2.7 | 346.6 | 343.9 |
DPO | 126.4 | 3.1 | (123.3) |
DWC | (33.9) | 173.8 | 207.7 |